Ulaştırma Kraliyet Komisyonu'nun (Royal Commission on Transport) Birleşik Krallık'ın trafik ve karayolu ağına ilişkin raporu.
173.178.57 · 1930 Δεκέμβριος · Αγγλική · makine üretimi, denetlenmedi
Tarama
Özgün metin (diplomatik transkripsiyon)
OCR: kontrollerden geçti · evren/qwen3-vl-30b
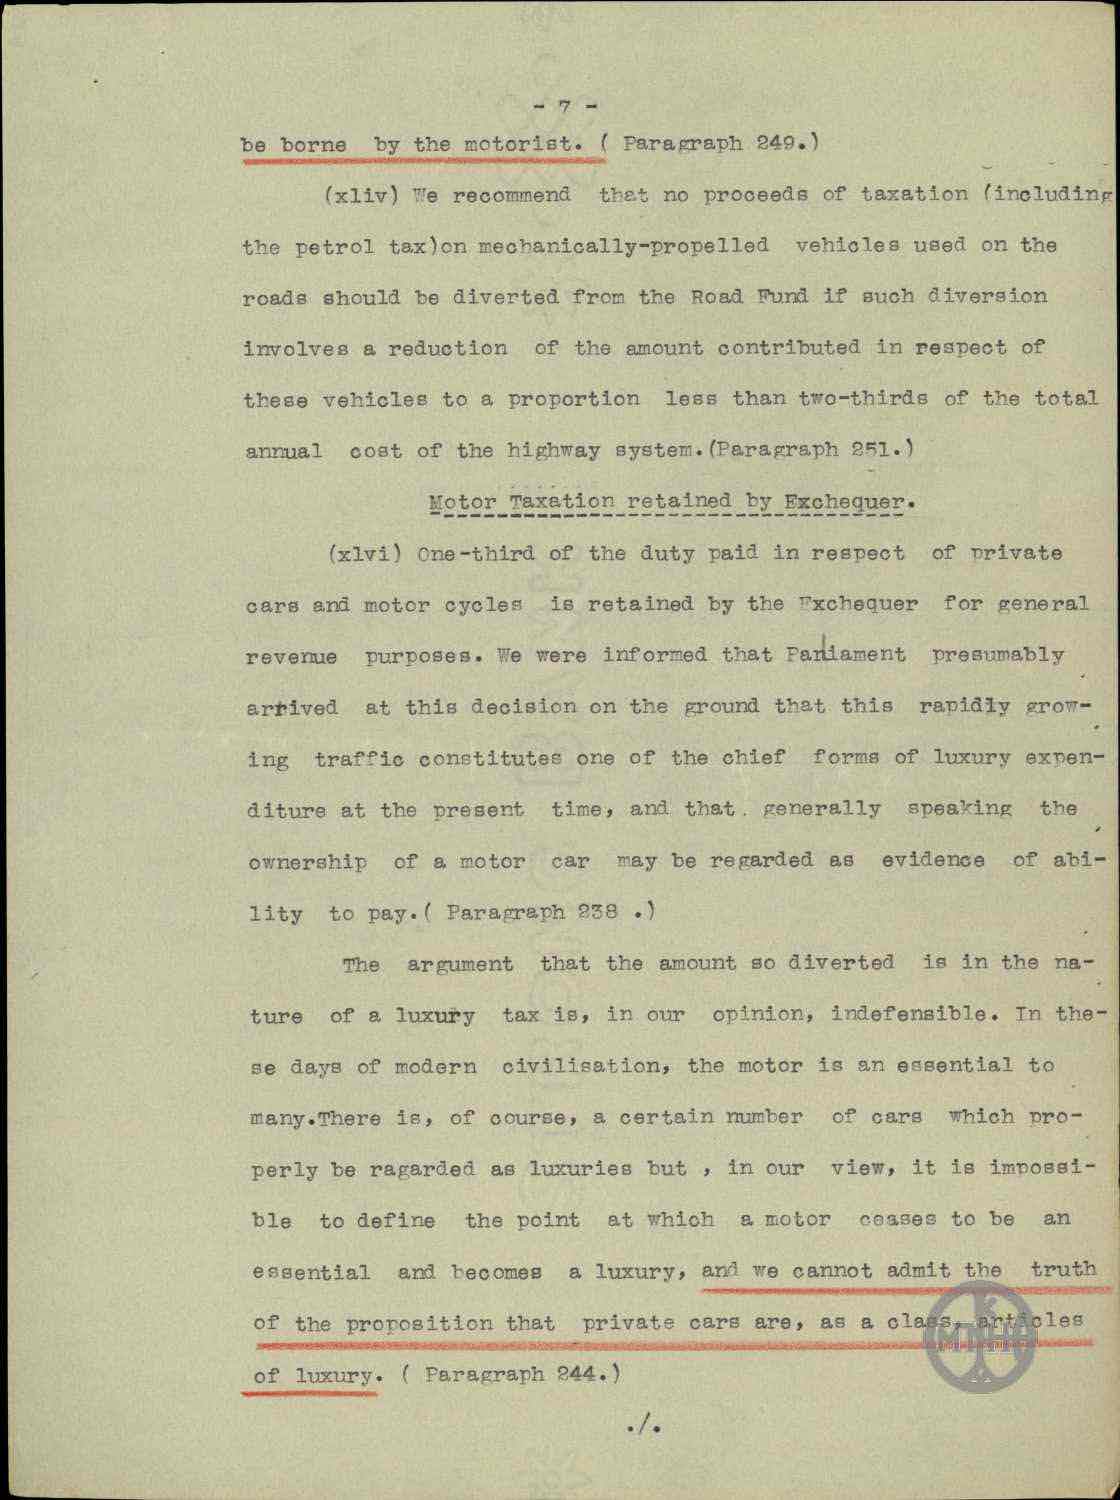
- 7 -
be borne by the motorist. (Paragraph 249.)
(xliv) We recommend that no proceeds of taxation (including the petrol tax) on mechanically-propelled vehicles used on the roads should be diverted from the Road Fund if such diversion involves a reduction of the amount contributed in respect of these vehicles to a proportion less than two-thirds of the total annual cost of the highway system. (Paragraph 251.)
Motor Taxation retained by Exchequer.
(xlvi) One-third of the duty paid in respect of private cars and motor cycles is retained by the Exchequer for general revenue purposes. We were informed that Parliament presumably arrived at this decision on the ground that this rapidly growing traffic constitutes one of the chief forms of luxury expenditure at the present time, and that, generally speaking the ownership of a motor car may be regarded as evidence of ability to pay. (Paragraph 238.)
The argument that the amount so diverted is in the nature of a luxury tax is, in our opinion, indefensible. In these days of modern civilisation, the motor is an essential to many. There is, of course, a certain number of cars which properly be regarded as luxuries but, in our view, it is impossible to define the point at which a motor ceases to be an essential and becomes a luxury, and we cannot admit the truth of the proposition that private cars are, as a class, articles of luxury. (Paragraph 244.)
./.
Damgalar ve notlar
- stamp ΜΠΗ/Benaki bottom right
- archival Page 8 of 11. top left
- archival Archivist's title: Έκθεση της Royal Commission on Transport σχετικά με το κυκλοφοριακό και οδικό δίκτυο του Ην. Βασιλείου. top left
- archival Date: 1930 Δεκέμβριος top left
- archival Document language (catalogue): Αγγλική top left
- archival Type: Έκθεση top left
Dimotiki Yunanca
Henüz yok.
Türkçe
- 7 -
motorlu taşıt sahibi tarafından karşılanmalıdır. (Paragraf 249.)
(xliv) Yollarda kullanılan motorlu taşıtlardan elde edilen vergi gelirlerinin (benzin vergisi dahil) hiçbir kısmının, bu aktarım söz konusu taşıtlar bakımından yapılan katkı tutarını karayolu sisteminin toplam yıllık maliyetinin üçte ikisinden daha düşük bir orana indirecekse, Yol Fonu'ndan başka amaçlara aktarılmamasını tavsiye ederiz. (Paragraf 251.)
Hazine Tarafından Alıkonulan Motorlu Taşıt Vergileri.
(xlvi) Hususi otomobiller ve motosikletler için ödenen verginin üçte biri, genel gelir amaçlarıyla Hazine tarafından alıkonulmaktadır. Bize bildirildiğine göre Parlamento, muhtemelen hızla artan bu trafiğin günümüzde lüks harcamanın başlıca biçimlerinden birini teşkil ettiği ve genel olarak bir otomobile sahip olmanın ödeme gücünün delili sayılabileceği gerekçesiyle bu karara varmıştır. (Paragraf 238.)
Bu şekilde aktarılan tutarın bir lüks vergisi niteliğinde olduğu yolundaki iddia, kanaatimizce savunulamaz. Modern medeniyetin bugünkü koşullarında otomobil pek çok kimse için zorunlu bir ihtiyaçtır. Elbette haklı olarak lüks sayılabilecek belirli sayıda otomobil vardır. Ancak bize göre bir otomobilin zorunlu bir ihtiyaç olmaktan çıkıp lüks hâline geldiği noktayı tanımlamak imkânsızdır. Hususi otomobillerin bir sınıf olarak lüks eşya olduğu önermesinin doğruluğunu da kabul edemeyiz. (Paragraf 244.)
./.
İngilizce
Henüz yok.